

Market Brief October Week 1
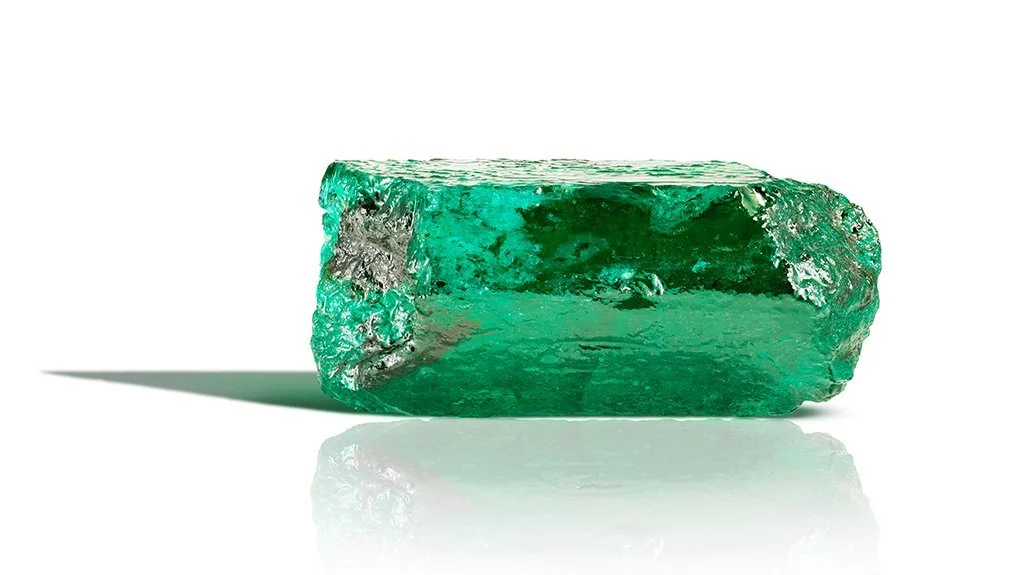
Emerald from Gemfields Auction in May: Mining Weekly
Market Snapshot
Gemfields sold every lot at its latest commercial-quality Kagem emerald auction, which closed on September 10, at an average of $9.72 per carat. That is 30% above the $7.46 achieved at the previous commercial sale in November and December 2025, and more than double the level of comparable sales in 2024. On its own, it makes it look like the market for ordinary Zambian emeralds is turning sharply upward. Read alongside the producer's own results and buyer data from Hong Kong, it describes something narrower: a price driven by competition and the pace at which supply reaches the market, rather than a general rise every seller can expect to share.
The auction detail shows how. All 44 lots and all 3.05 million carats offered found buyers, generating $29.6 million. Sixty-three companies placed bids, up from 55. Gemfields offered fewer carats than last time, 3.05 million against 3.41 million, after a nine-month gap between commercial sales. In a sealed-bid auction, the clearing price rises with the number of serious bidders even when no individual buyer's valuation changes, because each one must outbid more competitors to win. Eight more bidders competing for less material produced a higher price. The average is also not a like-for-like increase.
Gemfields states that lot composition differs between auctions, so the figure reflects what was offered as much as what any given stone would fetch. Gemfields' half-year results, released on September 30, supply the context. Kagem generated $26.7 million in the first half against $21.1 million a year earlier, with management describing production as strong and premium emerald recoveries as good, though operating costs remain elevated. Kagem had produced roughly 7.8 million carats of emerald by the end of August, ahead of the equivalent point in every prior year in the comparison Gemfields presented, and one higher-quality emerald auction remains scheduled before the end of the year. Zambian emerald is not scarce at the mine. Ruby is the opposite case. Gemfields booked a $125.2 million impairment on its Montepuez ruby mine and a $73.5 million first-half loss, adopting a more conservative forecast for premium ruby recoveries even while reporting some recent improvement. A producer writing down its own deposit on expected premium grade is conceding that the scarcity is structural.
China sets the limit on all of this. Jewelry & Gem World Hong Kong, held from September 14 to 20, drew 57,632 unique buyers, up 4.5% and a post-pandemic record. The growth came largely from outside mainland China: North American attendance rose 24.2% and European attendance 13.4%, with trade coverage attributed to Western retailers needing to restock, while mainland visitors rose 4.5%. China's official retail sales grew just 0.4% year on year in August, the slowest pace since May, and the statistics bureau acknowledged an acute imbalance between strong supply and weak demand. The buyer pool in the market Zambian miners mostly sell into is not expanding quickly.
Taken together, these developments describe a market in which the headline price and a seller's realized price have moved apart. The commercial emerald average was produced under conditions an individual miner rarely has: sorted and consistent lots, in-person inspection, and dozens of processors bidding against each other for a limited offering. Mine supply is plentiful, so scarcity is not carrying the price. Chinese demand is subdued, so a crowd of new buyers is not carrying it either. What carried it was competition and the pace of release, and those are features of how the stones were sold, not of the stones themselves.
Miner Insights
The practical meaning of this week's data is that $9.72 per carat is not the price of a miner's commercial emerald. It is the price of a particular way of selling it, and the distance between that figure and what most miners actually receive is explained largely by how stones change hands rather than by what they are.
The auction combined three conditions that all work for the seller: lots consistent enough that a buyer can trust a sample, inspection that removes doubt about the contents, and many buyers bidding at once. Compare how most small parcels are sold. A miner shows mixed material to one buyer, often under time pressure, and negotiates. With no competitor to outbid, the buyer prices the lot according to how few alternatives the miner appears to have. That is not necessarily unfair dealing. The buyer is simply pricing the absence of competition, and the seller pays for it. Two selling structures applied to identical stones can produce very different results.
This matters more than usual for miners selling into China this quarter. In a strong market, buyers compete for good parcels without being prompted, because there are more buyers than supply. The China data says that is not the current condition. Mainland attendance in Hong Kong grew far more slowly than Western attendance, and national retail growth in August was 0.4%. A Zambian miner selling into China cannot rely on a crowded buyer pool to bid a parcel up. Whatever competition exists for the stones will have to be arranged by the seller.
Supply strengthens the same conclusion. Kagem is producing emerald faster than in any recent year, with another higher-quality auction due before the end of the year, and buyers know comparable material keeps arriving. A miner claiming that commercial emerald is scarce will not be believed, and does not need to be. The full sell-through and the rise in bidders show that well-sorted commercial goods have genuine demand. What they need is a presentation that allows buyers to compete for them.
Ruby runs the other way. When the market's leading ruby miner writes down its own deposit because it expects fewer premium stones, the scarcity is confirmed by the party with most reason to report otherwise. Miners holding vivid, untreated ruby do not need to manufacture competition for it. They need to resist discounting it.
For emerald, the realized price is now set less by the stone and more by the structure of the sale. The consistency of the lot, and the number of buyers making firm offers at the same time, are where the gap between the headline and the price received is opened or closed.
Export & Compliance
No new regulatory change affecting Zambian gemstone exports has been identified since the last brief. The 15% export duty on precious stones and metals remains suspended, but exporters should verify the current duty, royalty, and permit position directly with MRC or ZRA before shipment. Mineral analysis, royalty clearance, production records, and security clearance remain required before goods leave the country.
The logistics cost picture has worsened. Brent crude has held above $100 a barrel since early September, up from around $82 at the time of our July brief, which feeds directly into air freight fuel surcharges on East Africa to Asia routes. Reported Strait of Hormuz transit figures now diverge sharply between tracking providers because many vessels are crossing with transponders switched off, so no single figure should be relied on. Re-quote freight immediately before shipment rather than using any rate obtained earlier in the quarter.
On grading language, the CIBJO congress in Vicenza concluded on September 7, after which its board ruled that synthetic should be the sole descriptor for man-made stones. Its published outcomes included no ruling on premium color descriptors for natural stones.
Opportunity of the Week
The opportunity this week is commercial-grade Zambian emerald, which for much of the past two years was the hardest material to sell and is now clearing with full sell-through and more competing buyers than at any recent sale.
These briefs have consistently directed attention toward premium material, and with reason. In September 2024, commercial emerald averaged $4.47 per carat, and Gemfields withdrew 18 of 46 lots that failed to reach reserve. That is no longer the condition. The latest commercial sale cleared every lot, drew eight more bidding companies than the one before, and averaged more than double the September 2024 level. Miners who have been holding commercial-grade emerald because it would not move now have a market for it. One caution applies: this sale followed a nine-month gap between commercial auctions, and Kagem is producing at a record pace, so the next commercial sale will show whether this level holds.
The price will be earned by preparation rather than handed over by the headline. The material that cleared was sorted into consistent lots that buyers could assess quickly and bid on confidently. Mixed commercial parcels, where a few better stones sit among many weak ones, do not reproduce those conditions and will not be valued as though they did. The work that turns commercial stock into saleable stock is sorting it into lots consistent in colour, size range, and clarity, so that a buyer looking at a sample can trust it represents the whole. Commercial and premium emeralds are different opportunities and should be sold differently. Premium material depends on documentation and a buyer with a defined use for it.
Commercial material depends on consistency and on volume a processor can plan production around. A miner holding both should keep them apart. Combining them pulls the premium valuation down without lifting the commercial one.
SAVVY is not purchasing stones at this time. We will announce in this brief when purchasing resumes.
Practical Tip
Before accepting any offer this week, get firm written prices from more than one buyer on the same parcel at the same time.
Prepare a single description of the lot: total weight, number of pieces, size range, colour range, clarity, treatment status if known, recovery area, and photographs taken in daylight with the stones laid out together. Send that identical description to each buyer you are speaking with on the same day, and ask each one the same question: "What is your firm price for this lot, how long does the offer stand, and what are your payment and delivery terms?"
Sending the same information to every buyer at once matters more than it sounds. When buyers receive different descriptions at different times, their offers cannot be compared, and the first offer tends to become the anchor for every conversation that follows. When they receive identical information on the same day, each one has to price the lot knowing that others are pricing it too. That is the pressure that lifted the commercial auction average, scaled down to a single parcel.
Ask for firm prices with a stated validity period rather than indicative ranges. A range lets a buyer revise downward after seeing the stones. A firm price with a date is a commitment you can compare.
Then compare the offers on net terms, not headline price. A higher figure with slower payment, longer consignment, or delivery risk may be worth less than a lower one paid promptly. The aim is not to find the highest number. It is to find the best offer you can actually collect, and to know it was made in competition rather than in isolation.